All articles
Medicare Savings Programs: who pays your $202.90 Part B premium
Three state-run programs pay the Medicare Part B premium for people under published lines: $1,350, $1,616 and $1,816 a month for one person in 2026, sharing a $9,950 resource limit. Enrollment brings Extra Help with drug costs automatically. MACPAC measured participation at 53, 32 and 15 percent, and the form never arrives on its own.
Are Medicare Advantage plans going away? What a plan exit actually means
The program isn't being eliminated. A company may decline to renew its contract for any reason, which ends the plans under it, and the rule requires a mailed notice at least 90 days ahead. How to tell a change notice from a termination notice, and the Medigap right that closes 63 days after coverage ends.
SNAP after 60: the 4 rules, and the October 1, 2026 reset
A household with a member 60 or older skips the gross income test. Medical costs over $35 come off income, Medicare premiums included, the shelter deduction has no cap, and the asset limit ignores the home. One hypothetical household, run two ways, comes out at $25 or $133. Every figure resets October 1.
Social Security COLA 2027: what is decided, and what isn't
The 2027 raise is arithmetic, not a vote. The base is locked at 317.265, July 2026 is the only published month at 3.1% above it, SSA's actuaries estimate 2.7%, and neither is the determination. Then $202.90 comes out for Part B, with a hold-harmless rule most people never hear named.
Will Medicare pay for a nursing home? The 100-day cliff
Medicare pays for short-term skilled nursing care, not for living in a nursing home. The 2026 ladder is $0 a day for days 1 to 20 after the $1,736 deductible, $217 a day for days 21 to 100, and everything after that is yours. None of it starts without a 3-day inpatient hospital stay, and nights spent under observation do not count toward those three days.
Are Medicare premiums tax deductible? The line on the return
Part B and Part D premiums are deductible medical expenses, and for most retirees that is worth exactly nothing. Schedule A lines 1 through 4, the 7.5%-of-AGI floor, the standard deduction that eats what survives, and the self-employed path on Schedule 1 line 17 that skips both.
You keep the higher check, not both
71.5% at 60, up to 100% at survivor full retirement age, and the $255 lump sum. Plus the fact the explainers bury: there is no online application, you call and say Survivor.
Past $24,480, your check shrinks — the money is not gone
Claim before full retirement age and keep working, and SSA withholds $1 of benefit for every $2 you earn over $24,480 in 2026. The withholding is real and the usual conclusion is not: SSA's Office of the Chief Actuary puts "lost" in scare quotes on its own page, and the agency's manual says the adjustment at full retirement age is automatic, with no form to file. Both 2026 limits, what counts as earnings and what SSA ignores, its own two worked examples, the honest limit on what you recover, and the one way this money genuinely can disappear.
How to file a Medicare IRMAA appeal — and the form most people actually need
Social Security says you probably should not file an appeal at all. The eight life-changing events, which tax year goes in Step 2, the exact evidence SSA requires, and the four ways to file Form SSA-44.
Is Social Security Checking Your Bank Account? Yes — But Not Yours
A warning is circulating that SSA will start checking senior bank accounts before September. Something real did change — on May 4, 2026, EM-25046 REV made account verification mandatory on every new SSI claim allowance, regardless of what the applicant says they own. It is not September, it does not reach people already on SSI, and there is no resource test in retirement or SSDI at all. What it does change, the $2,000 limit and the exclusions nobody quotes, and the joint-account rule that can count your balance against somebody else's limit — plus the named, dated, retroactive way to answer it.
Did Congress Cut Social Security? No — But 78% Is Real
Nothing has passed that cuts a Social Security check, and the bill people point at — H.R. 9187 — is still in committee. But the 2026 Trustees Report does project that the retirement and survivors fund pays 100% of scheduled benefits only until the fourth quarter of 2032, after which continuing income covers about 78% — and that share is projected to keep falling, to 62% by 2100. The 2034 and 83% figures you may have seen describe the hypothetical combined funds, which the Trustees say could not actually be combined without a change in the law. What the number measures, the two words that decode every version of this story, and a ten-second stress test on your own budget.
The $8 Credit Card Late Fee Cap Was Struck Down — Here's What Replaced It
The $8 late fee cap was announced in 2024, stayed, and then vacated by court order on April 15, 2025 — it never took effect a single day, and it only ever covered issuers with a million or more accounts. But killing it did not leave you unprotected: the older Regulation Z framework snapped back, with safe harbours of $30 and $41. The CFPB's own page still displays the 2017 figures, which is why so much of this is repeated wrong — and even the right numbers are ceilings, because an issuer may price by cost and a late fee can never exceed your required minimum payment.
Did the IRS Set a $10,000 Bank Account Limit? No — Here's the Real Rule
Somebody is telling seniors the IRS quietly set a new limit on your checking account. It did not. There is a real $10,000 figure in federal law — it covers cash, your bank files the report, and you file nothing. The three myths people get backwards, why splitting a deposit to stay under it is itself a federal crime even when the money is clean, and the threshold that actually moved in 2026: Form 1099-K is over $20,000 and more than 200 transactions, not $600.

Medicare Part D Premium Increase? What to Check Before Dec. 7
The headlines say the government is ending a Medicare subsidy. The honest version: a temporary program that held down premiums on standalone Part D plans ends after 2026, so the 2027 national base premium rises to $41.33 (your own plan may differ — final prices aren't public yet). What actually ended, whether your premium goes up, the Inflation Reduction Act protections that stay (the indexed out-of-pocket cap, no donut hole, the 6%/yr cap), who Extra Help shields, and exactly what to check during Open Enrollment before December 7.

Over 65? 5 Bills You May Be Able to Reduce or Eliminate
Not “everything is free after 65.” But five real government programs can reduce — and in some cases eliminate — recurring costs a lot of people over 65 still pay in full: the enhanced senior deduction, Lifeline, LIHEAP, Extra Help, and the Medicare Savings Programs that can cover the $202.90 Part B premium. Who qualifies, who each leaves out, and where to check. 2026 figures.

Your Social Security Earnings Record Is Probably Wrong — Here's the Fix
“File this ONE secret form for +$200.” It's overpromised — there's no magic form. But it's standing on something true: your check is built on your highest 35 years, and one wrong or missing year holds it down for life. The honest version — the gap between the check you're owed and the check you get, how to check free at ssa.gov/myaccount, and how to fix a real error with Form SSA-7008.
The RMD Tax Torpedo: One Forced Withdrawal at 73 Re-Prices 3 Taxes
“At 73, just take the minimum and pay the tax.” That misses the point. Your RMD isn’t a bill — it’s a trigger: the income can make up to 85% of your Social Security taxable, spike your Medicare premium two years later, and creep your bracket. The tax torpedo, plainly — plus three legal ways to soften it.

Why 37% of Widows Get a Smaller Social Security Check (The Widow’s Limit)
“Your Social Security decision is your own.” Not if you’re married. When one spouse dies the survivor keeps the higher check — capped at what the higher earner claimed. Claim early and you cap your widow’s income for life; ~37% of widows already lose this way.
The Roth conversion "deadline" was repealed. Here's the real one.
"Convert to a Roth now — before the tax cuts sunset." Claim check: that deadline was repealed — the 2017 brackets are now permanent (OBBBA, July 2025). The REAL deadline is a new $6,000-per-person senior deduction (2025–2028), and a Roth conversion is income — so converting "inside the window" can phase the deduction away at ~12¢ per dollar for a couple. The three-window model, the couples number nobody says out loud, and three people making the same call three different ways.

Is a "no-tax" state really cheaper to retire in?
"Move to a no-income-tax state and pay less." Claim check: often backwards. Income tax is only one of three doors — income, property, sales. A no-income-tax state (Texas: ~$8,000/yr property tax on a $500k home) can cost more than an income-tax state that exempts every dollar of retirement income (Pennsylvania, Illinois). The three-door model, the 2026 map, and three real cases.

Is the 22% Social Security cut in 2032 real?
"Social Security goes broke in 2032." Claim check: the 2032 date and the 22% cut are real — the do-nothing scenario in the new Trustees Report — but the check does not stop. Payroll taxes still fund ~78% of benefits, no cut has passed, and claiming early to beat it locks a bigger permanent cut. The tank-vs-pipe math, three real cases, and the calm move.

"No tax on Social Security"? Here's what actually changed
An SSA email said the law "eliminates federal income taxes on Social Security." Claim check: the tax was NOT ended — same combined-income rules as before. What passed is a $6,000 senior deduction (65+, 2025–2028) with phase-outs at $75k/$150k. Who gets it, who gets nothing, and the withholding trap.

Medicare's $50 weight-loss deal: who actually qualifies
The Medicare GLP-1 Bridge pays $50 a month for certain weight-loss drugs from July 2026 to December 2027 — but it's temporary, weight-only, and gated. Who qualifies (Part D plus the BMI gate), why a diabetes diagnosis pushes you off, which drugs are covered, and the $50 catch most people miss.
Full retirement age: the line your whole check is measured from
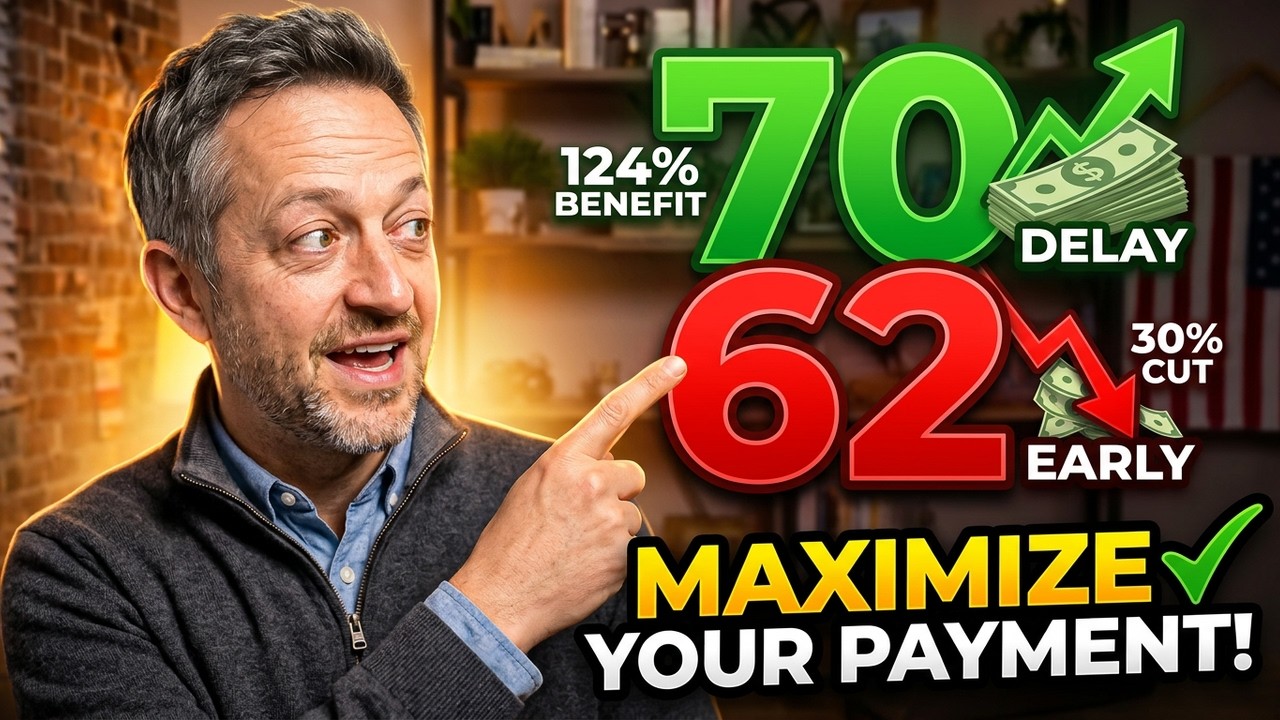
Claim at 62 and lock in a permanent 30% cut; wait to 70 and your check grows to 124%. What your FRA is by birth year, the earnings test that turns off at the line, and why couples must decide together.
July 2026 money changes: the $6,000 deduction, $2,100 drug cap, IRMAA
Three real changes retirees miss: the new $6,000 senior deduction and its phase-out, Medicare's $2,100 Part D drug cap, and the IRMAA surcharge set two years back. Plus the honest answer on your COLA raise.

IRMAA: the Medicare surcharge on higher incomes
The income-related surcharge on Part B & Part D: the two-year lookback, what counts as MAGI, the one-dollar cliff, and how to appeal it with Form SSA-44.
The widow's penalty: why taxes jump when a spouse dies
Income barely changes but the tax bill jumps: bracket compression, a halved standard deduction, more Social Security taxed, and the IRMAA spike — plus the legal fixes.
65+ and paying full property tax? The four tools
Almost every state gives homeowners 65+ a property-tax break — but it's never automatic. The four tools, the income myth, and how to claim yours.

Medicare enrollment at 65: windows & penalties
The three doors, the 7-month window, the COBRA trap, the Part B & Part D penalties that last for life, the Medigap window, and IRMAA.
When to claim: 62 vs 67 vs 70
70% at 62, 100% at 67, 124% at 70 — the benefit-by-age schedule, the 8%/yr delayed credits, the break-even age, and the survivor lever.

Who actually gets back pay? (WEP & GPO repeal)
The Social Security Fairness Act repealed WEP and GPO. Who's owed thousands, who's fixed automatically, who must file a claim — and who gets nothing.

Is your Social Security taxed?
The 0%/50%/85% rule, the combined-income formula, the 2026 thresholds, why it quietly gets worse every year, and 3 legal moves that lower it.

The new $6,000 senior tax deduction (2025)
Who qualifies (the 3 rules), how it stacks on your standard deduction, the income phase-out, and how to claim it on Schedule 1-A.